Is Now a Good Time to Buy?

Team Gill • September 1, 2016

If you’re getting tired of all the media headlines claiming impending housing market and economic doom and gloom, you’re not alone. It seems every time you browse the news another US economist is predicting terrible things for Canada. Articles like this one, claiming an ‘extreme bubble’ is just around the corner… note, not just a bubble… but an extreme bubble. 

The truth is, mortgage rates have never been lower and while low interest rates are somewhat blamed for increased house prices, low interest rates are good for borrowers who are looking to get into the market. So despite what the media would have us believe, now (historically speaking) is actually a pretty good time to buy a property.

Understanding that you can’t control the future, and of course past performance doesn’t indicate future direction, if you isolate the actual cost of borrowing money, you might be surprised at how cheap money is right now. Obviously buying a property is a personal decision, the time has to be right for you, and your finances have to be in order, but if the sensational media headlines are causing you to second guess yourself or the market, let’s have a look at the cost of borrowing today compared to previous years.

Fixed Interest Rates

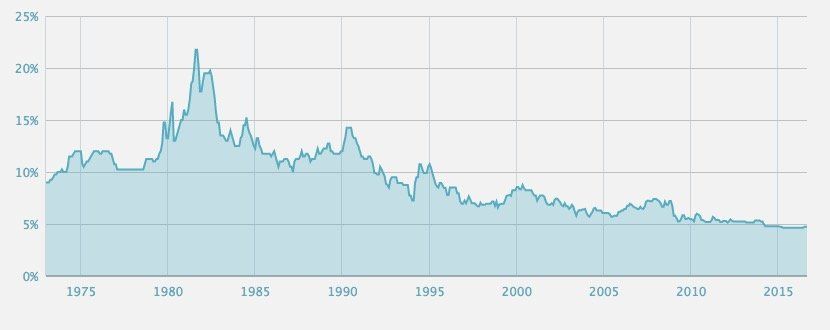
Fixed interest rates are at an all time low. Seriously, it has never been cheaper to borrow fixed money in Canada. Here is a handy chart that provides a visual to that effect, showcasing the historical posted 5 year mortgage rates from 1973 to today. 
Here are a couple points to note: 

  • In July of 1981, fixed rates were at 21.75%. 
  • 21.75% is a higher rate of interest than a lot of credit cards. Yikes!
  • In July of 2016, rates were at 4.74%.
  • 4.74% is a posted rate, a lot of broker channel lenders have discounted rates in the low 2% range.

Prime Rate

So, fixed rates are a little too permanent for you? No problems, the prime rate (the rate that sets the baseline for a variable rate mortgage) can be found hovering below half of the Canadian historical average. So here is another handy chart that provides a visual going back to 1935 up until today. 
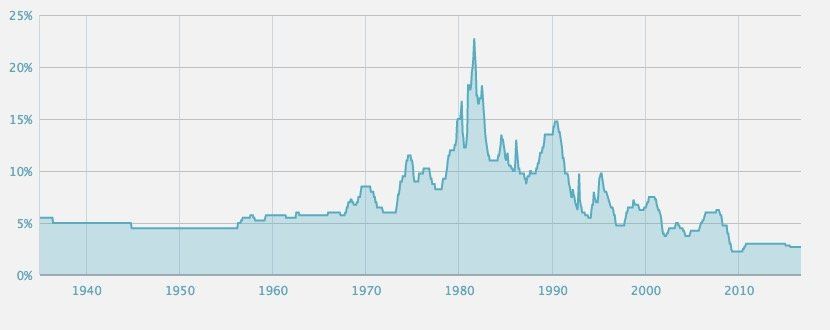
A couple points to note:

  • The 80s were not only bad for music and fashion, but a bad time to borrow money as well.
  • Although prime is 2.7%, lenders offer a variable component discount as well tied to the prime.
  • Discounts in today’s lending landscape are around half a percentage point.
  • The 40s, 50s, and 60s, were pretty steady, who knows, we might just be in for some more of that! 

Let’s Talk

So regardless if you prefer the fixed or variable, as you can see, it’s never been cheaper to borrow money. Period. Please don’t let the media scare you into thinking the market is about to implode, their job is to sell advertising not bring a balanced perspective to your newsfeed. Affordability is a personal thing and shouldn’t be dictated by a market you can’t control. 

If you would like to figure out what you can afford, and go over your financial situation to prepare for getting a mortgage, we’d love to help. Please contact us anytime, we would love to work with you. 


Share

Sign up to to our newsletter to hear weekly updates on market news, timely buyer/seller tips, and up to date rates
SIGN UP
Mick & Sheila Gill
CANADIAN MORTGAGE EXPERTS
RECENT POSTS 

By Team Gill • November 3, 2026
You’ve found the right home, your offer’s been accepted, and your financing is approved—congratulations! But before you can pick up the keys and celebrate, there’s one more important stage: the closing process. Closing is the final step in your homebuying journey, where all the paperwork, legal details, and financial transactions come together. It can feel overwhelming if you don’t know what to expect, but with the right preparation, closing can be smooth and stress-free. Here’s a step-by-step guide to help you understand the process. Step 1: Hire a Lawyer or Notary A real estate lawyer (or notary, depending on your province) handles the legal side of closing. They will: Review the purchase agreement and mortgage documents Conduct a title search to confirm the seller has the legal right to sell the property Ensure the mortgage lender is properly registered on the title Handle the transfer of funds between you, the lender, and the seller Your lawyer or notary will be your main point of contact during closing, so choose one you trust and who communicates clearly. Step 2: Finalize Your Mortgage Your lender will send the mortgage instructions directly to your lawyer or notary. At this stage: You’ll provide proof of property insurance (lenders require this before releasing funds) You’ll confirm your down payment and closing costs are available in your lawyer’s trust account The lawyer will prepare all documents for your review and signature Step 3: Pay Closing Costs Closing costs typically range from 1.5% to 4% of the purchase price. These can include: Legal fees Title insurance Land transfer tax (where applicable) Adjustments for property taxes or utilities prepaid by the seller Home inspection or appraisal fees (if not already paid) Your lawyer will provide a final statement of adjustments so you know exactly how much is due on closing day. Step 4: Sign the Paperwork A few days before closing, you’ll meet with your lawyer or notary to sign all the necessary documents, including: Mortgage agreement Title transfer Insurance confirmations Statement of adjustments Bring valid government-issued ID to this appointment. Step 5: Transfer of Funds On the day of closing: Your lender sends the mortgage funds to your lawyer Your lawyer combines these funds with your down payment and pays the seller Legal ownership of the property is transferred into your name The lender is registered on title as a secured creditor Step 6: Get the Keys! Once the paperwork is filed and the funds have cleared, your lawyer will confirm that the transaction is complete. You’ll then get the keys to your new home—officially making it yours. The Bottom Line The closing process is a series of important steps, but with the right team in place, it doesn’t have to be stressful. By working closely with your mortgage professional and lawyer, you’ll have guidance every step of the way—from signing the documents to turning the key in the front door. If you’d like help preparing for the closing process—or want a clear breakdown of your own closing costs— connect with us today.
By Team Gill • October 28, 2026
On October 28, 2026, the Bank of Canada raised its key interest rate by 0.25%, bringing it to 2.5%. If you have a mortgage, are shopping for a home, or have a renewal coming up, this decision matters. Here is a plain-language look at what changed, why it happened, and what it could mean for you.