Divorce and Your Mortgage: What You Need to Know

Team Gill • February 10, 2026

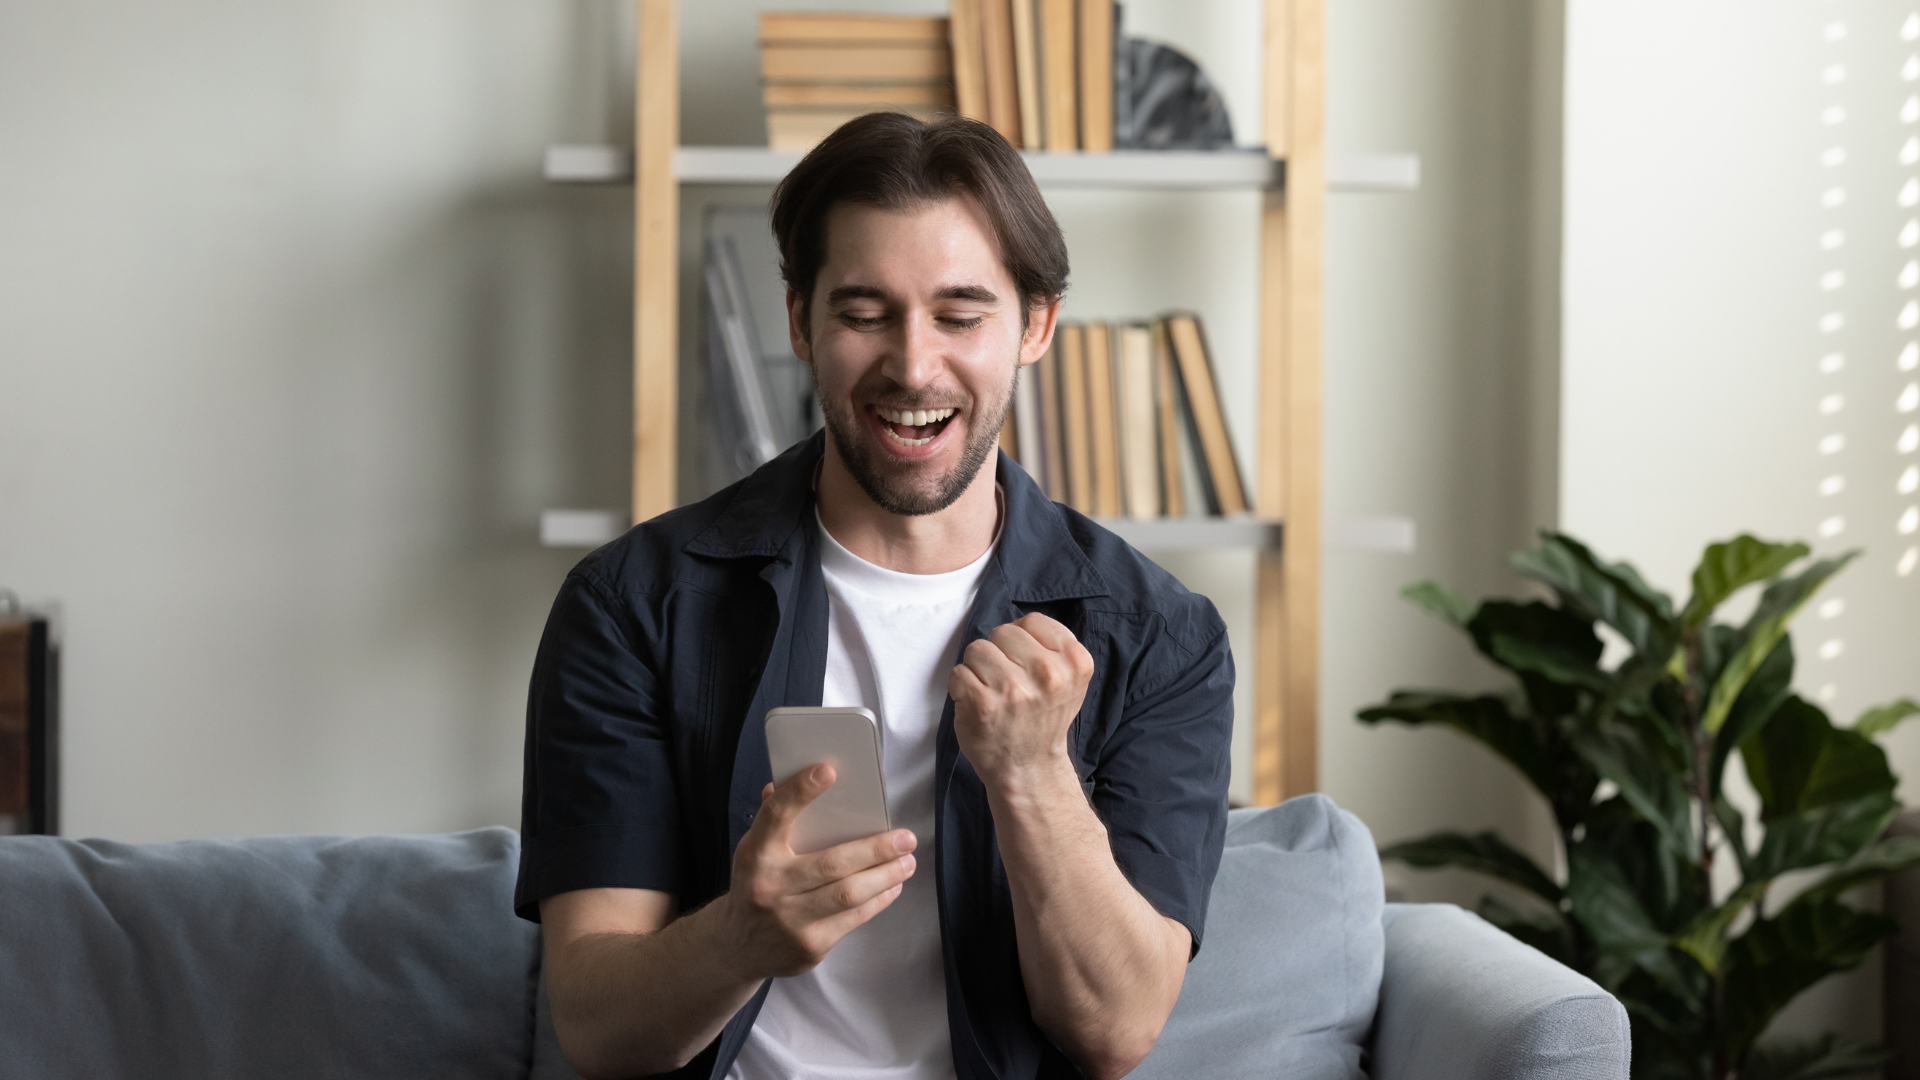
Going Through a Separation? Here’s What You Need to Know About Your Mortgage
Separation or divorce can be one of life’s most stressful transitions—and when real estate is involved, the financial side of things can get complicated fast. If you and your partner own a home together, figuring out what happens next with your mortgage is a critical step in moving forward.


Here’s what you need to know:


You’re Still Responsible for Mortgage Payments

Even if your relationship changes, your obligation to your mortgage lender doesn’t. If your name is on the mortgage, you’re fully responsible for making sure payments continue. Missed payments can lead to penalties, damage your credit, or even put your home at risk of foreclosure.


If you relied on your partner to handle payments during the relationship, now is the time to take a proactive role. Contact your lender directly to confirm everything is on track.


Breaking or Changing Your Mortgage Comes With Costs

Dividing your finances might mean refinancing, removing someone from the title, or selling the home. All of these options come with potential legal fees, appraisal costs, and mortgage penalties—especially if you’re mid-term with a fixed-rate mortgage.


Before making any decisions, speak with your lender to get a clear picture of the potential costs. This info can be helpful when finalizing your separation agreement.


Legal Status Affects Financing

If you're applying for a new mortgage after a separation, lenders will want to see official documentation—like a signed separation agreement or divorce decree. These documents help the lender assess any ongoing financial obligations like child or spousal support, which may impact your ability to qualify.


No paperwork yet? Expect delays and added scrutiny in the mortgage process until everything is finalized.


Qualifying on One Income Can Be Tougher

Many couples qualify for mortgages based on combined income. After a separation, your borrowing power may decrease if you're now applying solo. This can affect your ability to buy a new home or stay in the one you currently own.


A mortgage professional can help you reassess your financial picture and identify options that make sense for your situation—whether that means buying on your own, co-signing with a family member, or exploring government programs.


Buying Out Your Partner? You May Have Extra Flexibility

In cases where one person wants to stay in the home, lenders may offer special flexibility. Unlike traditional refinancing, which typically caps borrowing at 80% of the home’s value, a “spousal buyout” may allow you to access up to 95%—making it easier to compensate your former partner and retain the home.


This option is especially useful for families looking to minimize disruption for children or maintain community ties.


You Don’t Have to Figure It Out Alone

Separation is never simple—but with the right support, you can move forward with clarity and confidence. Whether you’re keeping the home, selling, or starting fresh, working with a mortgage professional can help you understand your options and create a strategy that aligns with your new goals.


Let’s talk through your situation and explore the best path forward. I’m here to help.


Share

Sign up to to our newsletter to hear weekly updates on market news, timely buyer/seller tips, and up to date rates
SIGN UP
Mick & Sheila Gill
CANADIAN MORTGAGE EXPERTS
RECENT POSTS 

By Team Gill • September 22, 2026
For most Canadians, buying a home isn’t possible without a mortgage. And while getting a mortgage may seem straightforward—borrow money, buy a home, pay it back—it’s the details that make the difference. Understanding how mortgages work (and what to watch out for) is key to keeping your borrowing costs as low as possible. The Basics: How a Mortgage Works A mortgage is a loan secured against your property. You agree to pay it back over an amortization period (often 25 years), divided into shorter terms (ranging from 6 months to 10 years). Each term comes with its own interest rate and rules. While the interest rate is important, it’s not the only thing that determines the true cost of your mortgage. Features, penalties, and flexibility all play a role—and sometimes a slightly higher rate can save you thousands in the long run. Key Questions to Ask Before Choosing a Mortgage How long will you stay in the property? Your timeframe helps determine the right term length and product. Do you need flexibility to move? If a work transfer or lifestyle change is possible, portability may be important. What are the penalties for breaking the mortgage early? This is one of the biggest factors in the real cost of borrowing. A low rate won’t save you if breaking costs you tens of thousands. How are penalties calculated? Some lenders use more borrower-friendly formulas than others. It’s not easy to calculate yourself—get professional help. Can you make extra payments? Prepayment privileges allow you to pay off your mortgage faster, potentially saving years of interest. How is the mortgage registered on title? Some registrations (like collateral charges) can limit your ability to switch lenders at renewal without extra costs. Which type of mortgage fits best? Fixed, variable, HELOCs, or even reverse mortgages each have their place depending on your financial and life situation. What’s your down payment? A larger down payment could reduce or eliminate mortgage insurance premiums, saving thousands upfront. Why the Lowest Rate Isn’t Always the Best Choice It’s tempting to chase the lowest rate, but mortgages with rock-bottom pricing often come with restrictive terms. For example, saving 0.10% on your rate may put a few extra dollars in your pocket each month, but if the mortgage has harsh penalties, you could end up paying thousands more if you break it early. The goal isn’t just the lowest rate—it’s the lowest overall cost of borrowing . That’s why it’s so important to look beyond the headline number and consider the whole picture. The Bottom Line Mortgage financing in Canada is about more than rate shopping. It’s about aligning your mortgage with your financial goals, lifestyle, and future plans. The best way to do that is to work with an independent mortgage professional who can walk you through the fine print and help you secure the product that truly keeps your costs low. If you’d like to explore your options—or review your current mortgage to see if it’s really working in your favour—let’s connect. I’d be happy to help.
By Team Gill • September 8, 2026
Cashback Mortgages: Are They Worth It? Here’s What You Need to Know If you’ve been exploring mortgage options and come across the term cashback mortgage , you might be wondering what exactly it means—and whether it’s a smart move. Let’s break it down in simple terms. What Is a Cashback Mortgage? A cashback mortgage is just like a regular mortgage—but with one extra feature: you receive a lump sum of cash when the mortgage closes . This cash is typically: A fixed amount , or A percentage of the total mortgage , usually between 1% and 7% , depending on your mortgage term and lender. The money is tax-free and paid directly to you on closing day. What Can You Use the Cashback For? There are no restrictions on how you use the funds. Here are some common uses: Covering closing costs Buying new furniture Renovations or home upgrades Paying off high-interest debt Boosting your cashflow during a tight transition Whether it’s to help you settle in or catch up financially, cashback can offer a helpful buffer— but it comes at a cost . The True Cost of a Cashback Mortgage Here’s the part many people overlook: cashback mortgages come with higher interest rates than standard mortgages. Why? Because the lender is essentially advancing you a small loan upfront—and they’re going to make that money back (and then some) through your mortgage payments. So while the upfront cash feels like a bonus, you’ll pay more in interest over time to have that convenience. Breaking Down the Numbers It’s hard to give a blanket answer about how much more you’ll pay since it depends on: Your interest rate The cashback amount The mortgage term Your payment schedule This is why it’s important to run the numbers with a mortgage professional who can help you compare this option with others based on your personal financial situation. Are You Eligible for a Cashback Mortgage? Not everyone qualifies. Cashback mortgages generally come with stricter requirements . Lenders often want to see: Excellent credit history Strong, stable income Low debt-to-income ratio If your mortgage file includes anything “outside the box”—like being self-employed or recently changing jobs—qualifying for a cashback mortgage might be tough. What If You Need to Break the Mortgage? This is one of the biggest risks with cashback mortgages. If your circumstances change and you need to break your mortgage early, you could be on the hook for: Paying back some or all of the cashback you received, and A prepayment penalty (typically the interest rate differential or 3 months’ interest—whichever is higher) That can be a very expensive combination. So if there’s even a chance you might need to sell, refinance, or move before your term is up, a cashback mortgage might not be the best fit. Should You Consider a Cashback Mortgage? Maybe—but only with eyes wide open. Cashback mortgages can be helpful in the right scenario, but they’re not free money. They’re a lending tool that benefits the lender , and the key is knowing exactly what you’re agreeing to. Final Thoughts: Talk to an Expert First Choosing the right mortgage isn’t just about the lowest rate or the biggest perk—it’s about making a choice that fits your whole financial picture. If you’re considering a cashback mortgage, or just want to explore all your options, let’s talk. As an independent mortgage professional , I can help you weigh the pros and cons of various products, so you can make a confident, informed decision. Have questions? I’d be happy to help—reach out anytime.