Budget 2018 | British Columbia

Team Gill • February 21, 2018

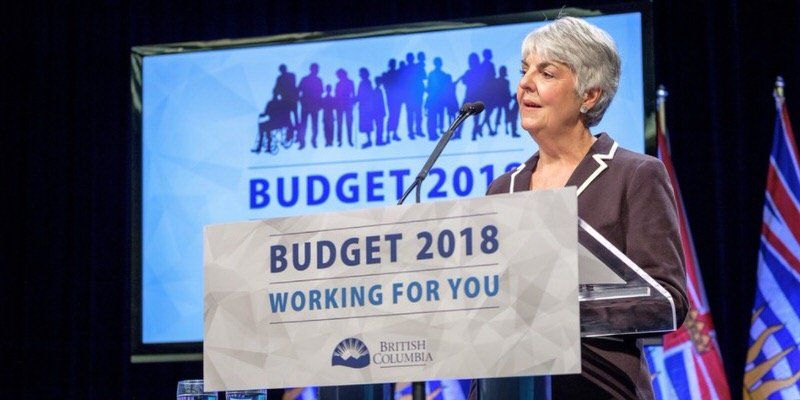
The BC Government released Budget 2018 today. As it relates to housing, the government made changes to the foreign buyers tax, and added a new speculation tax.

Foreign Buyers Tax –  This is really an enhancement to the tax that is already in place, effective Wednesday, the government will increase the foreign buyers tax from 15% to 20%.The tax will be extended to the Fraser Valley, the capital regional districts in Victoria and Nanaimo and the Central Okanagan Regional Districts, instead of simply being applied in Metro Vancouver.

Speculation Tax –  This new, annual property tax will apply to foreign and domestic homeowners who do not pay income tax in B.C., including those who leave their properties vacant. The new tax will initially apply to homes in Metro Vancouver, the Fraser Valley and capital regional districts in Victoria and Nanaimo, Kelowna and West Kelowna. In 2018, the tax rate will be 0.5 per cent of assessed value. In 2019, it will rise to 2.0 per cent of assessed value.


News release:


Highlights:


Share

Sign up to to our newsletter to hear weekly updates on market news, timely buyer/seller tips, and up to date rates

SIGN UP
Mick & Sheila Gill
CANADIAN MORTGAGE EXPERTS
RECENT POSTS 

By Team Gill • October 28, 2026
On October 28, 2026, the Bank of Canada raised its key interest rate by 0.25%, bringing it to 2.5%. If you have a mortgage, are shopping for a home, or have a renewal coming up, this decision matters. Here is a plain-language look at what changed, why it happened, and what it could mean for you.
By Team Gill • October 20, 2026
Owning a home feels great—carrying a large mortgage, not so much. The good news? With the right strategies, you can shorten your amortization, save thousands in interest, and become mortgage-free sooner than you think. Here are four proven ways to make it happen: 1. Switch to Accelerated Payments One of the simplest ways to reduce your mortgage faster is by moving from monthly payments to accelerated bi-weekly payments . Instead of 12 monthly payments a year, you’ll make 26 half-payments. That works out to the equivalent of one extra monthly payment each year, shaving years off your mortgage—often without you noticing much difference in your budget. 2. Increase Your Regular Payments Most mortgages allow you to boost your regular payment by 10–25%. Some even let you double up payments occasionally. Every extra dollar goes directly toward your principal, which means less interest and faster progress toward paying off your balance. 3. Make Lump-Sum Payments Depending on your lender, you may be able to make lump-sum payments of 10–25% of your original mortgage balance each year. This option is ideal if you receive a bonus, inheritance, or other windfall. Applying a lump sum directly to your principal immediately reduces the interest charged for the rest of your term. 4. Review Your Mortgage Annually It’s easy to put your mortgage on auto-pilot, but a yearly review keeps you in control. By sitting down with an independent mortgage professional, you can check if refinancing, restructuring, or adjusting terms could save you money. A quick annual review helps ensure your mortgage is always working for you—not against you. The Bottom Line Paying off your mortgage early doesn’t require a massive lifestyle change—it’s about making smart, consistent choices. Whether it’s accelerated payments, lump sums, or regular reviews, every step you take helps reduce your debt faster. If you’d like to explore strategies tailored to your situation—or want a free annual mortgage review—let’s connect. I’d be happy to help you find the fastest path to mortgage freedom.